 Saiteja
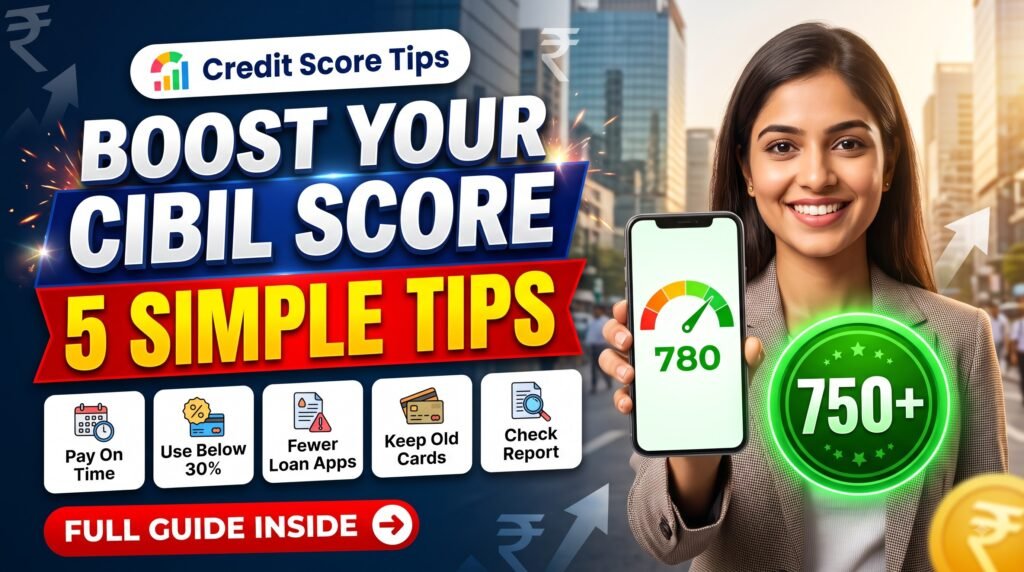
Improve CIBIL score and you get faster loan approvals, lower interest rates and higher credit card limits, because lenders trust a score above 750.
Is your loan or credit card application getting rejected? A CIBIL score of 750 or above is generally considered good by most lenders. Here are five simple habits that help build a strong score.
Table of Contents
CIBIL Score Range
| Score | Meaning |
|---|---|
| 750 – 900 | Good / Excellent |
| 650 – 749 | Fair |
| Below 650 | Needs improvement |
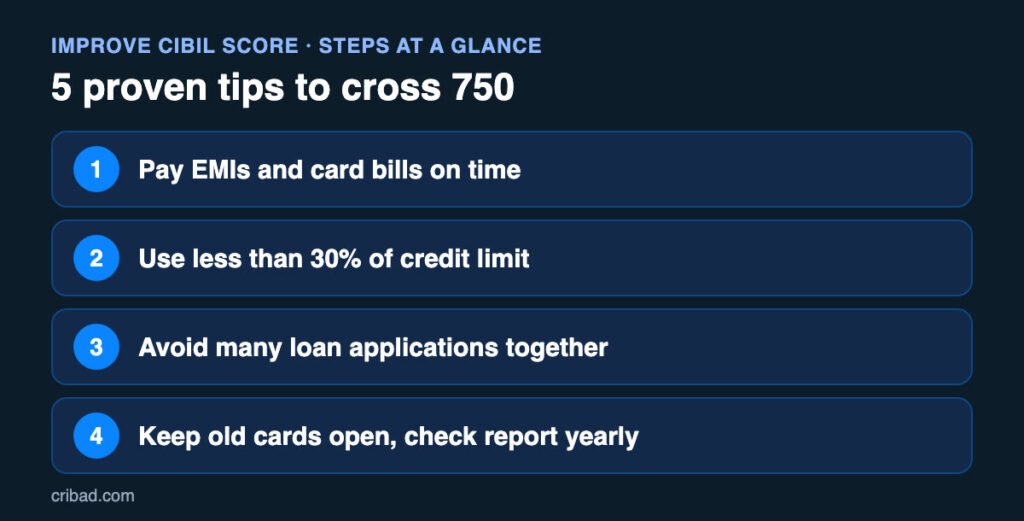
Tip 1: Always Pay EMIs and Card Bills on Time
Payment history is the biggest factor. Even one late payment can reduce your score. Set auto-pay or reminders before the due date.
Tip 2: Use Less Than 30% of Your Credit Limit
If your card limit is ₹1,00,000, try to keep your usage below ₹30,000. High usage shows credit hunger and can lower your score.
Tip 3: Do Not Apply for Many Loans at Once
Every application creates a hard enquiry. Many enquiries in a short time make lenders think you badly need credit. Apply only when needed.
Tip 4: Keep Old Credit Cards Open
A long credit history helps your score. Closing your oldest card reduces your average credit age and total limit.
Tip 5: Check Your Credit Report Every Year
Get your free credit report once a year from CIBIL, Experian, Equifax and CRIF. If you see mistakes or unknown loans, raise a dispute.
What Affects Your CIBIL Score the Most
- Payment history: paying EMIs and card bills on time is the biggest factor
- Credit utilisation: how much of your card limit you use
- Credit age: how old your accounts are
- Credit mix: a healthy mix of secured and unsecured loans
- Hard enquiries: how many times you applied for new credit recently
To improve CIBIL score, work on these factors one by one. Payment history and utilisation make the fastest difference.
Improve CIBIL Score: 30-Day Action Plan
- Download your free credit report and check for errors
- Pay any overdue amount immediately
- Bring card usage below 30% of the limit
- Set auto-pay for every EMI and card bill
- Stop new loan or card applications for 6 months
Most people see the score start to move within 2 to 3 billing cycles after these changes.
Myths About How to Improve CIBIL Score
- Checking your own score does not reduce it
- Closing old cards does not help; it often hurts
- Having no loans does not mean a high score; you need some credit history
- Settling a loan is not the same as closing it; settled accounts hurt the score
Watch the Video
How Lenders Use Your Score
When you apply for a loan or credit card, the lender checks your credit report and score to decide two things: whether to approve your application, and at what interest rate.
- 750 and above: high chance of approval and better interest rates
- 700 to 749: approval is likely, but the rate may be slightly higher
- 650 to 699: approval may need extra documents or a co-applicant
- Below 650: many lenders may reject the application
Even a small difference in interest rate makes a big difference on a long loan. On a home loan of ₹30 lakh for 20 years, a rate that is just 0.5% lower can save you lakhs of rupees in total interest. That is why building a good score is worth the effort.
If you are new to credit and have no history, start with a small credit card or a secured card against a fixed deposit. Use it for a few small expenses every month and pay the full bill on time. Within six to twelve months, you will build a healthy credit history.
Avoid becoming a guarantor for someone else’s loan unless you trust them fully. If they miss payments, your score is also affected.
Frequently Asked Questions
Does checking my own score reduce it?
No. Checking your own score is a soft enquiry and does not affect it.
How long does it take to improve the score?
With consistent on-time payments and low usage, many people see improvement in a few months, but it depends on your credit history.
Can I improve CIBIL score in one month?
Small improvements are possible after one billing cycle, but a strong score usually takes 3 to 6 months of good habits.
Does a credit card help improve CIBIL score?
Yes, if you use it lightly and pay the full bill on time every month.
Does a home loan or car loan help my credit history?
Yes. A secured loan such as a home loan or car loan, repaid on time every month, shows lenders that you can handle long-term credit responsibly. Over the years, this steady record of payments builds a strong history and supports a higher score.
What should I do if my report has a mistake?
Raise a dispute on the credit bureau website with proof, such as a loan closure letter or payment receipt. The bureau checks with the lender and corrects the report if the error is confirmed.
Related Guides
- RBI UDGAM Portal: How to Find Unclaimed Bank Deposits of Your Family (Step by Step)
- PMSBY and PMJJBY: Get ₹2 Lakh Insurance for Just ₹20 and ₹436 a Year
- How to Lock Aadhaar Biometrics and Stop AePS Fraud (Step by Step)
Official source: CIBIL official website. Always verify the latest rules on the official website.
Conclusion
Building a good CIBIL score is about simple habits followed every month. Start today and your next loan will be easier and cheaper.
Disclaimer: This article is for information purposes only and is not financial advice. Lenders use their own criteria for approval.